The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
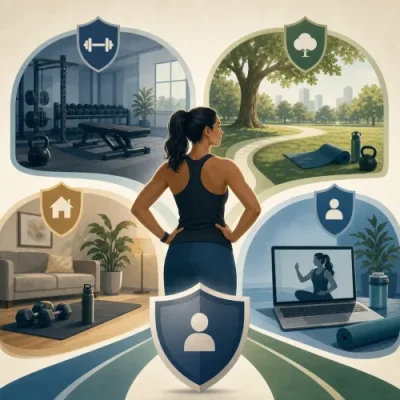
Where you train clients can change your risk exposure. This guide explains insurance considerations for Australian personal trainers working in gyms, parks, client homes, studios, boot camps and online.
Personal trainers often work across more than one setting: a commercial gym in the morning, a client's home after work, a weekend boot camp in a park, and online programming between sessions. Each setting can create different risks, contract requirements and insurance questions.
This article explains how a personal trainer's work environment may affect insurance considerations in Australia. It is general information only and does not take into account your business model, contracts, qualifications, clients, locations or insurer criteria.
Why your work setting matters for personal trainer insurance
A personal trainer insurance policy is usually assessed against what you do, where you do it, who you train and how you deliver your services. A trainer who works only as an employee inside one gym may have different exposures from an independent contractor running outdoor group sessions, visiting homes and selling online programs.
Work setting can affect:
- Public liability exposures, such as injury to a client or member of the public, or damage to property at a venue.
- Professional indemnity exposures, such as allegations that your advice, programming, screening or instruction caused loss or injury.
- Contractual requirements, including minimum cover limits, certificates of currency, indemnity clauses or the need to note a venue as an interested party.
- Equipment risks, especially if you carry portable gear between locations or store equipment in a vehicle, home or studio.
- Policy scope, including whether online training, group classes, outdoor sessions or subcontracted work are included.
For a broader overview of insurance for personal trainers, you can also visit Personal Trainers Insurance Online. The sections below focus specifically on how different work settings may change the questions you ask before arranging or reviewing cover.
Working in commercial gyms
Many personal trainers operate inside gyms as employees, contractors, franchisees or licence holders. Insurance considerations can vary significantly depending on that arrangement.
If you are an employee, the gym may hold certain business insurance policies, but that does not automatically mean every claim connected to your conduct, advice or side business is covered. If you also train private clients, run sessions away from the gym, sell programs under your own brand or contract to multiple venues, you may need to check how your own cover responds.
If you are an independent contractor or licence holder, the gym may require you to provide a certificate of currency before you can use the facility. Venue contracts may also specify minimum public liability limits, professional indemnity requirements, permitted activities, hygiene obligations, incident reporting processes and rules about using gym-owned equipment.
Questions to ask before training in a gym
- Does the gym's contract require you to hold your own public liability or professional indemnity insurance?
- Are you covered only while training inside that specific facility, or also for external sessions?
- Does the policy cover your particular services, such as strength training, small group classes, rehabilitation-style programs, nutritional guidance or online coaching?
- Who is responsible if gym equipment fails, is misused or is damaged during your session?
- Are you required to follow the gym's screening, induction, supervision and incident reporting procedures?
It can be useful to have contracts reviewed before assuming your insurance matches the venue's requirements. The site's brokers page may be a relevant next step if you need help discussing policy suitability or venue requirements with a qualified professional.
Outdoor personal training insurance considerations
Outdoor personal training can include one-on-one sessions in parks, beach workouts, running groups, boot camps and circuit classes in public spaces. These settings often introduce risks that are less controlled than a gym environment.
Outdoor risk factors can include uneven surfaces, weather, poor lighting, nearby pedestrians, dogs, cyclists, shared facilities and limited access to first aid equipment. Public spaces can also create exposure to third parties who are not your clients, such as a passer-by tripping over equipment or being struck by a resistance band, ball or weight.
Depending on the location, a council, land manager or venue owner may require a permit, booking, risk assessment or evidence of public liability insurance before you conduct commercial sessions. Requirements can differ between councils and locations, so trainers should check the rules for each area where they operate rather than assuming one approval applies everywhere.
Outdoor and park-based sessions: practical checks
- Confirm whether a permit, booking or council approval is needed for commercial training.
- Check whether your policy covers outdoor personal training and the specific activities you run.
- Consider weather, lighting, ground conditions and emergency access before each session.
- Keep equipment compact, visible and safely positioned away from public pathways where possible.
- Use client screening, warm-up processes and class management appropriate to the environment.
Outdoor sessions can be flexible and appealing, but they may require more active risk management because you have less control over the space.
Training clients in their homes
Mobile personal trainer insurance considerations are different again when you travel to client homes, apartment gyms or private properties. You are entering an environment you do not control, and each home may have different flooring, space constraints, pets, children, stairs, furniture and access issues.
Common exposures include accidentally damaging a client's property, a client tripping over your equipment, or injury occurring during an exercise in a space that is not suitable for the movement. If you bring portable equipment, you may also need to consider theft, loss or damage while travelling between sessions.
Before training in a home, it is sensible to assess the space, confirm the client has enough room for the planned session, document relevant health screening information and adapt exercises to the environment. A waiver or disclaimer may help clarify expectations, but it should not be treated as a substitute for appropriate insurance, safe programming or professional judgement.
Running sessions in your own or rented studio
Some trainers rent a studio, lease a room inside a wellness centre, share a small facility with other professionals or operate from a home-based training space. These arrangements may bring additional responsibilities because you may have greater control over the premises, equipment and client experience.
Depending on the arrangement, you may need to think about:
- Property and contents cover for equipment you own, lease or store on site.
- Public liability for clients, visitors or contractors attending the premises.
- Lease or hire agreement requirements, including minimum insurance levels or obligations to repair damage.
- Subcontractors or other trainers, including whether they need their own insurance and whether your policy responds to their actions.
- Business interruption exposure if an insured event prevents you from using the space.
If you operate from home, you should not assume your domestic home and contents policy automatically covers commercial training activities. Home business use, client visits and business equipment can have different insurance implications and should be checked with the relevant insurer or adviser.
Boot camps and group classes
Boot camps, group fitness and circuit classes can increase the number of people exposed to risk at one time. Even if exercises are simple, the combination of multiple participants, varied fitness levels, shared equipment and limited one-on-one supervision can change the risk profile.
Insurance considerations for boot camp insurance in Australia may include whether the policy covers group training, maximum participant numbers, outdoor locations, casual attendees, trial classes, subcontracted instructors and higher-risk activities. If children, older adults, pre- or post-natal clients or clients with known health conditions attend, additional care may be needed in screening, programming and supervision.
Risk management for group sessions often includes clear session boundaries, visible equipment placement, participant screening, suitable progressions and documented incident procedures. Trainers should also consider how they record attendance, injuries, medical disclosures and modifications given during a class.
Online fitness coach insurance considerations
Online coaching may feel lower risk because the trainer is not physically present, but it can still create professional exposure. Clients may rely on your exercise programming, technique cues, progression advice, nutritional guidance or general health and fitness recommendations.
Online fitness coach insurance considerations can include whether your policy covers remote coaching, pre-recorded programs, live video sessions, app-based training, written programs, challenges, email advice and clients located outside your usual area. Some policies may have territorial limits, jurisdiction conditions or exclusions that matter if you coach people interstate or overseas.
Remote delivery also makes communication and record keeping especially important. You may not be able to observe form, environment or fatigue as closely as you would in person. Clear instructions, client screening, progress notes and boundaries around the scope of your advice can help reduce misunderstandings.
Hybrid trainers: when one policy needs to match several settings
Many trainers combine several formats. For example, you might contract at a gym, run two outdoor group sessions each week, visit clients at home and sell online training plans. In that situation, it is important to describe your full operating model when seeking or reviewing cover.
A useful review can include:
- all locations where you train clients, including gyms, parks, homes, studios and online platforms;
- the services you provide, such as one-on-one sessions, group classes, boot camps, online programs or general nutrition guidance;
- your client types, including any higher-risk or specialised groups;
- the equipment you own, transport, lend to clients or store at venues;
- contracts with gyms, councils, landlords or corporate clients;
- whether you use subcontractors, assistants or other instructors;
- where your clients are located, particularly for online coaching; and
- how you screen clients, record consent and manage incidents.
This is where personal trainer insurance coverage becomes less about buying a generic label and more about matching the policy to the way your business actually operates.
How work setting may affect the cost of cover
Personal trainer insurance cost can vary because insurers may consider factors such as business activities, annual turnover, claims history, locations, equipment values, number of trainers, client types, cover limits and optional policy sections. A trainer conducting low-volume one-on-one sessions may present different underwriting considerations from a business running large outdoor boot camps across several council areas.
Price should not be the only comparison point. A cheaper policy may not be appropriate if it excludes a core part of your work, such as outdoor sessions, online coaching, group classes or subcontractors. Likewise, a broader policy may include features you do not need. Policy suitability and pricing depend on individual circumstances and insurer criteria.
A setting-based insurance checklist for personal trainers
| Work setting | Common insurance questions |
|---|
| Commercial gym | Does the venue require your own insurance, a certificate of currency or specific cover limits? Are you covered as an employee, contractor or separate business? |
| Park or public space | Is a council permit required? Does your policy cover outdoor sessions, boot camps and injury to members of the public? |
| Client home | Are property damage and portable equipment risks considered? Can you safely adapt sessions to each home environment? |
| Rented or owned studio | Do lease obligations, equipment, contents, visitors and subcontractors create extra cover needs? |
| Group class or boot camp | Are participant numbers, supervision, screening and group activities within policy scope? |
| Online coaching | Does the policy cover remote advice, written programs, digital delivery and clients outside your local area? |
When to review your personal trainer insurance policy
It is worth reviewing your policy whenever your work setting changes. This might include moving from employment to contracting, adding outdoor sessions, renting a studio, launching online coaching, hiring another trainer or expanding into corporate wellness sessions.
You may also want to read more about public liability obligations for Australian personal trainers if you are unsure how injury or property damage claims can arise. For broader policy selection factors, the guide to choosing the right insurance for your personal training business may also be helpful.
The main point is simple: where and how you train clients matters. Before relying on a policy, check whether it reflects your actual services, locations, contracts and client base. If you are unsure, consider seeking guidance from an appropriately qualified insurance professional.
Published: Sunday, 20th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.